
Invoice vs Receipt vs Proforma Invoice: What's the Real Difference?
Invoice vs receipt vs proforma invoice is a genuinely confusing comparison, because all three documents can look nearly identical – a header, an itemized list, a total amount – while meaning completely different things legally and practically. Using the wrong one at the wrong stage of a transaction can create real problems, from confused clients to invalid tax claims.
The One-Line Version First
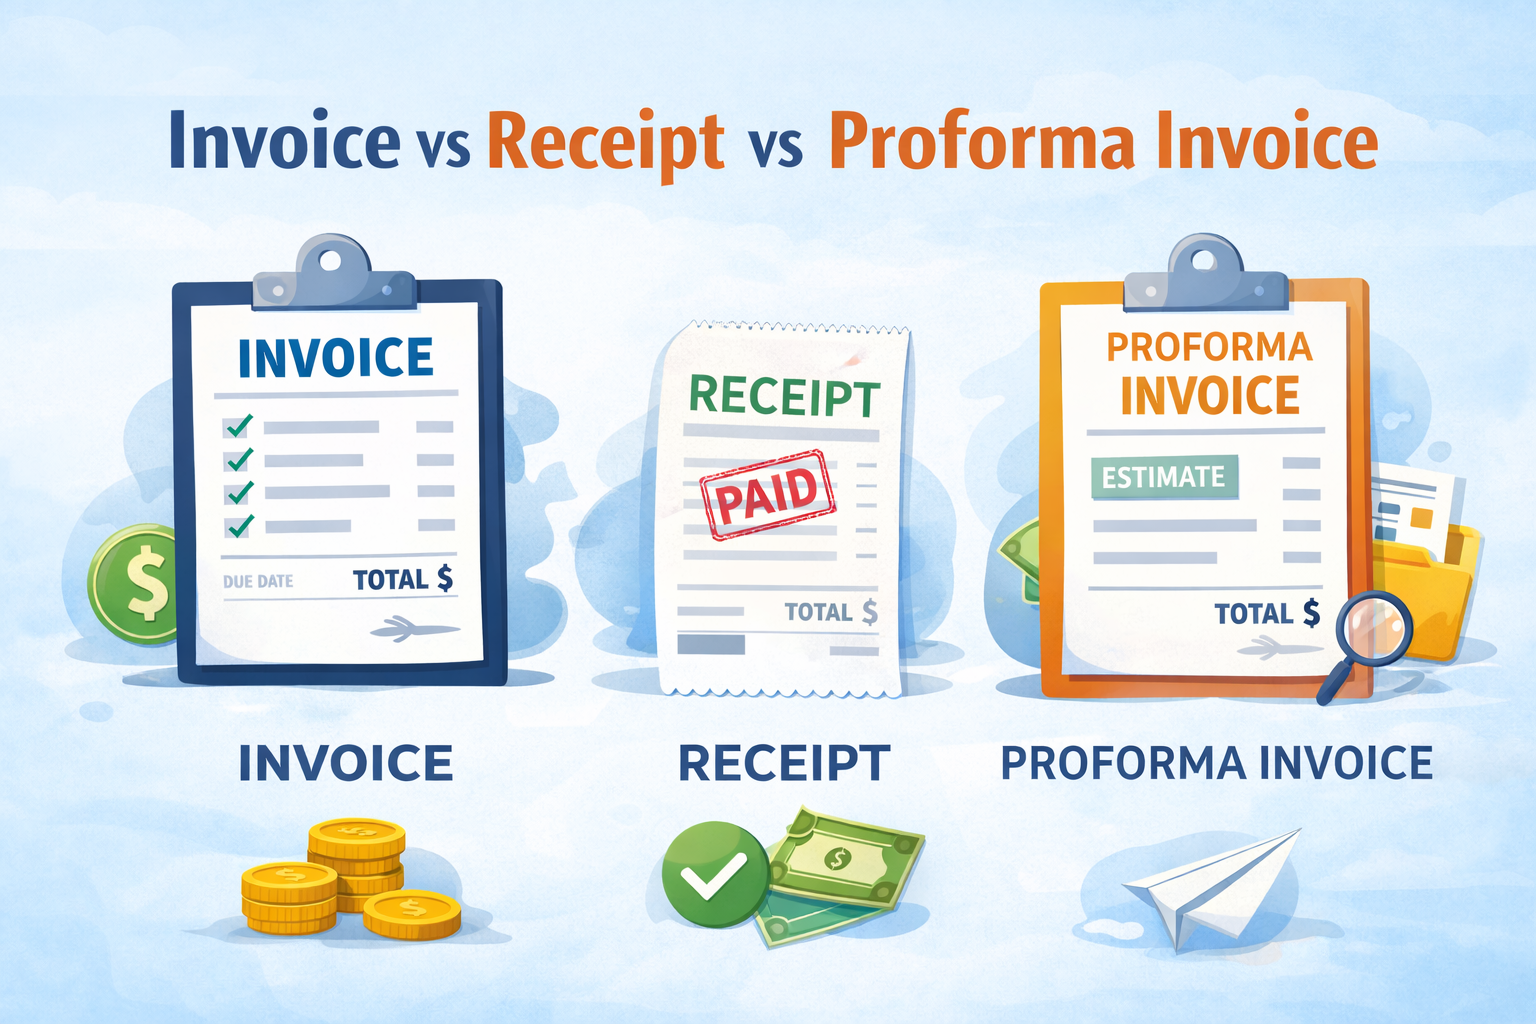
An invoice requests payment for something already delivered or agreed. A receipt confirms payment has already been received. A proforma invoice previews what an invoice will look like, before the transaction is finalized. The difference is entirely about timing and legal weight, not formatting.
What an Invoice Actually Is
A tax invoice is a legally binding demand for payment, issued once goods or services have been delivered (or, in some cases, at the time of delivery). Under GST rules, a valid tax invoice must contain specific mandatory fields – invoice number, GSTIN, tax breakdown, and more – and it’s the document a GST-registered buyer needs to claim Input Tax Credit (ITC) on that purchase.
Once issued, an invoice creates a genuine payment obligation. If the buyer doesn’t pay, the invoice itself is the evidence of what’s owed.
What a Receipt Actually Is
A receipt is issued after payment has been received – it’s proof that money changed hands, not a request for money. A receipt typically shows the amount paid, the date, the payment method, and what it was for, but it doesn’t need the full GST field set an invoice requires, since it’s not a tax document used for ITC claims.
There’s one important exception: if you’re GST-registered and receive an advance payment for services before the work is delivered, the receipt you issue isn’t just an ordinary receipt – it’s a receipt voucher, a specific document required under Rule 50 of the CGST Rules and Section 31(3)(d) of the CGST Act. This matters because GST liability on services generally arises at the time of receiving the advance, not later when the work is finished, so the receipt voucher carries real tax significance a plain payment confirmation doesn’t. It must show your GSTIN, a serial number, the amount, and the applicable tax rate (or 18% provisionally, if the exact rate isn’t yet determinable). This requirement generally applies to services; advances for goods are usually not taxed at the time of receipt, so an ordinary receipt is typically sufficient there.
One more practical detail freelancers often miss: under Section 186 of the Income Tax Act, 2025 (the current citation, replacing the earlier Section 269ST from April 1, 2026), you cannot legally accept ₹2 lakh or more in cash from a single client in a day, for a single transaction, or across payments tied to one event – regardless of whether you issue a receipt for it. A receipt documents a payment; it doesn’t make an otherwise non-compliant cash payment acceptable.
What a Proforma Invoice Actually Is
A proforma invoice is a preview, not a binding demand. It’s typically sent before work begins or before a sale is finalized, showing the client exactly what the final invoice will look like – the goods or services, quantities, prices, and estimated tax – so they can review terms, arrange internal approvals, or confirm budget before committing.
Critically, a proforma invoice has no legal standing as a tax invoice. It cannot be used to claim Input Tax Credit, and it doesn’t create a formal payment obligation on its own. If terms change after a proforma invoice is sent – the price, the scope, the timeline – the actual invoice issued later can differ from it.
Example: One Transaction, Three Documents
Say you’re a freelance consultant working with a new client on a project worth ₹1,00,000.
1. Proforma invoice: sent before the project starts, showing the estimated cost and scope, so the client’s finance team can approve the budget.
2. Tax invoice: sent after the work is delivered, now a binding request for the agreed ₹1,00,000 (plus applicable GST if registered), with full GST-compliant fields.
3. Receipt: sent after the client actually pays, confirming the ₹1,00,000 has been received, with the payment date and method noted.
Same transaction, three different documents, each doing a different job at a different stage.
Why Mixing These Up Causes Real Problems
Using a proforma invoice as if it were a tax invoice means the buyer can’t claim ITC on it – a genuine compliance issue if they later try to. Sending a receipt without ever having issued a proper invoice leaves no formal record of what was actually owed, which becomes a problem if there’s ever a dispute or an audit. And treating an invoice as if it were merely informational, rather than a binding payment demand, can create confusion about whether payment is actually due.
Common Mistakes
1. Calling a proforma invoice a “quote” or “estimate” interchangeably, then treating it as legally binding when it isn’t
2. Skipping the tax invoice entirely and only issuing a receipt after payment, leaving no formal record of what was owed
3. Using proforma invoice numbers in the same sequence as tax invoices, creating confusion in your own records
4. Assuming a receipt satisfies GST invoicing requirements, when it doesn’t contain the mandatory fields a tax invoice needs
5. Not updating the final invoice when terms changed after the proforma invoice was sent
FAQ (Frequently Asked Questions)
Can I skip the proforma invoice and go straight to a tax invoice?
Yes, for smaller or repeat clients this is common. Proforma invoices are most useful when a client needs formal approval before committing, such as with new corporate clients or larger projects.
Does a receipt need to follow GST invoice rules?
No. A receipt confirms payment already received; it isn’t the document used to claim Input Tax Credit, so it doesn’t need the full mandatory field set a tax invoice requires.
Can a proforma invoice be used for GST purposes?
No. A proforma invoice has no legal standing as a tax document and cannot be used to claim Input Tax Credit or as proof of a completed transaction.
What if the final invoice amount differs from the proforma invoice?
That’s normal if scope or terms changed after the proforma was sent – the final tax invoice reflects the actual agreed amount, not the earlier estimate.
If a client pays me an advance before I start the work, is a normal receipt enough?
Not if you’re GST-registered and the advance is for services – you’re generally required to issue a receipt voucher instead, since GST typically becomes payable on that advance right away. A plain receipt is usually fine for advances on goods, where GST isn’t charged at the time of receipt.
What are the three types of invoices people usually mean by this?
Most commonly: a proforma invoice (a preview sent before the transaction is finalized), a tax invoice (a binding demand for payment after delivery), and sometimes a receipt is loosely grouped in as the third, even though it technically confirms payment rather than requesting it.
What comes first – a purchase order or a proforma invoice?
There’s no single universal order; it depends on the industry. A seller sometimes issues a proforma invoice first, which the buyer’s purchase order then confirms. In other cases, the buyer issues a purchase order first, and the seller responds with a proforma invoice matching those terms.
Final Takeaway
Invoice vs receipt vs proforma invoice comes down to one question: what stage is this transaction at? A proforma invoice previews terms before work begins, a tax invoice demands payment after delivery, and a receipt confirms payment already received. Using each at the right stage – and never treating one as a substitute for another – keeps both your records and your GST compliance clean.
This article explains general invoicing practices and isn’t personal financial or legal advice. For your specific situation, a chartered accountant can confirm what applies to you.
Sources & References
– Central Board of Indirect Taxes and Customs (CBIC) – tax invoice requirements under Rule 46 of the CGST Rules, and receipt voucher requirements under Rule 50 and Section 31(3)(d) of the CGST Act – https://www.cbic.gov.in/
– Income Tax Department (Government of India) – cash receipt restrictions under the Income Tax Act, 2025 – https://www.incometax.gov.in/
Pingback: GST On Invoices In India